
conscious capital
When Philanthropy Should Go First: Using Catalytic Capital to Unlock Commercial Investment
Ajay Wasserman,
Founder, author, host of Conscious Capital
6 minutes
22 September 2026
Listen to the podcast here
Audio Title: When Philanthropy Should Go First: Using Catalytic Capital to Unlock Commercial Investment
Description:Discover how philanthropy uses catalytic capital to de-risk emerging markets, build shared infrastructure, and unlock commercial investment in Africa.
Table of Contents
Introduction
There is a persistent belief that philanthropy should stay away from commercial enterprise. Donations are for social needs; investment is for business. Mixing the two, some argue, risks subsidising private profit.
That concern is valid. Philanthropic money can distort markets, reward weak operators and protect investors from risks they should carry themselves.
But there are also moments when philanthropy is precisely the capital that should go first—not to make a bad business look investable, but to create the evidence, capability and infrastructure without which a good market cannot emerge.
The distinction is important.
The work commercial capital cannot reasonably fund
Commercial investors need a credible line of sight to return. That does not make them short-sighted or uncaring. It is the mandate attached to their capital.
Some of the most important work required before an investment can succeed has no direct revenue stream. Who pays to map thousands of smallholder farms before an agricultural platform can underwrite supply? Who funds the clinical protocols and accreditation work that make a network of primary-care clinics investable? Who develops standard contracts, environmental studies or community agreements before an infrastructure project reaches financial close?
These activities create value for many future participants, but the first party paying for them may not be able to capture that value. Economists call this a market failure. Investors experience it as a missing piece of the deal.
Philanthropy can fund that missing piece.
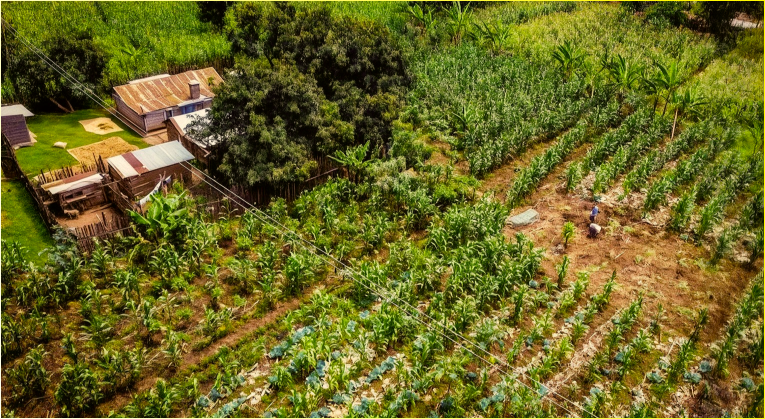
Aerial mapping of smallholder farms in Nairobi, Kenya, unlocking commercial investment.
Source: AgFunderNews
Go first where the market is missing information
Many emerging-market opportunities are not rejected because they are fundamentally weak. They are rejected because the risk is difficult to understand.
A commercial lender may have no data on repayment performance in a new agricultural value chain. An investor may not know whether low-income households will consistently pay for a new service. An insurance provider may lack the claims history needed to price a product. A municipality may not have the technical capacity to prepare an investable project.
Catalytic grants can fund pilots, baseline data, independent evaluation and project preparation. The objective is not to produce another report. It is to convert uncertainty into evidence that investors can price.
This is one reason catalytic technical assistance matters. OECD work on blended finance highlights how institutional capacity, regulatory reform and technical support can strengthen the environment in which private capital operates. Sometimes the highest-leverage use of philanthropy is not inside a transaction at all. It is in removing the obstacle that prevents many transactions.
Build the market’s foundations
Philanthropy should also go first when the necessary infrastructure is shared.
A digital identity system, quality standard, credit-information mechanism, farmer traceability platform or training curriculum may benefit an entire sector. No single early-stage enterprise should be expected to carry the full cost, especially when competitors will later use the same foundation.
Funding these common assets can lower the cost of participation and improve standards across the market. It can help local enterprises compete on the quality of their service rather than on who can afford to build basic infrastructure from scratch.
This is where catalytic capital can be more powerful than a permanent grant programme. It finances the conditions for enterprise rather than replacing enterprise.
The design must remain open and fair. Shared infrastructure should not become a hidden subsidy to one favoured company. Access rules, data governance and ownership need to be clear from the beginning.
First-loss capital needs boundaries
Philanthropy can also take financial risk directly. A first-loss tranche or guarantee can persuade other investors to enter a market they perceive as too uncertain.
Used well, this can reveal the true risk of a new segment and build a track record. Used badly, it can hide weak underwriting and transfer losses from private investors to donors.
The test is whether the protection addresses a specific, temporary barrier. The amount should be limited. The trigger should be clear. The commercial investors should still have meaningful capital at risk. The structure should collect data that makes future protection more accurately priced and, ideally, less necessary.
IFC’s blended-finance approach stresses additionality, minimum concessionality, commercial sustainability and avoiding market distortion. Philanthropic capital should apply the same discipline even when it is not legally required to do so.
If the guarantee must grow every time the business expands, the market may not be graduating. If investors receive normal commercial returns while being protected from normal commercial losses, the structure is not catalytic. It is a subsidy.
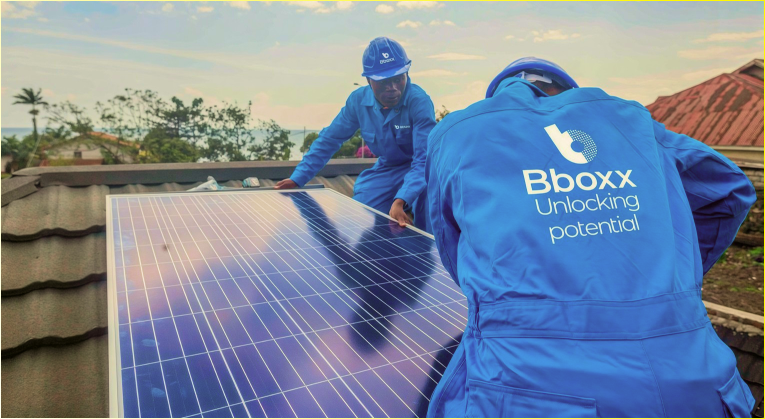
Bboxx, Nairobi, Kenya: De-risking off-grid solar loans to mobilise commercial capital.
Source: GuarantCo
The discipline of an exit plan
Every catalytic intervention should begin with an answer to a simple question: what must become true for this support to end?
Perhaps lenders need three years of repayment data. Perhaps a clinic network must reach a certain standard of governance and occupancy. Perhaps a project pipeline must become large enough for preparation costs to be recovered commercially. Perhaps a regulator needs the systems and skills to take over a function.
The milestones will differ, but the principle should not. Philanthropy should have a theory of graduation, not only a theory of change.
That does not mean every grant must produce a financial return. The return may be a functioning institution, a trusted dataset, a safer market or a group of enterprises that can finally attract ordinary capital. What matters is that the intervention leaves capacity behind.
Philanthropy should leave a stronger market behind
The most respectful form of philanthropy is not endless rescue. It is enabling people and institutions to stand on stronger foundations.
There are times when commercial capital should go first because the risk is commercial and the return belongs to the investor. There are times when government should act because the need is a public responsibility. And there are times when philanthropy is uniquely able to absorb the uncertainty before anyone else can responsibly invest.
Its role is to take the first step that unlocks the next one.
When used with discipline, catalytic capital does not crowd out investment. It makes responsible investment possible—and then allows itself to become unnecessary.