
conscious capital
Blended Finance Without the Buzzwords: Who Should Take Which Risk?
Ajay Wasserman,
Founder, author, host of Conscious Capital
6 minutes
15 September 2026
Listen to the podcast here
Audio Title: Blended Finance Without the Buzzwords: Who Should Take Which Risk?
Description:Cut through the jargon of blended finance. Discover how allocating specific risks to the right capital providers helps solve genuine market failures.
Table of Contents
Introduction
Blended finance is often explained through diagrams full of tranches, guarantees and acronyms. The structure looks sophisticated, but the purpose can become difficult to see.
At its core, blended finance is much simpler: different types of capital take different risks so that an investment with real development value can become commercially viable.
The central question is not how many layers the structure contains. It is whether each risk has been placed with the party best able—and properly mandated—to carry it.
Start with the obstacle, not the instrument
A project does not need blended finance merely because it operates in Africa or has an impact story.
It needs blending when a specific market failure prevents otherwise useful private investment. The obstacle might be first-mover risk, an unproven technology, a lack of long-term local-currency funding, a weak project pipeline, high early transaction costs, uncertain demand or the absence of reliable data.
These are different problems and should not receive the same solution.
If the project is commercially sound but lenders lack confidence in a new market, a partial guarantee may be enough. If the underlying economics are viable but the preparation work is too early for investors, grant-funded technical assistance may be appropriate. If cash flows take longer to mature than commercial lenders can tolerate, patient subordinated capital may bridge the gap. If the business can never cover its operating costs, no amount of clever blending will turn it into a sustainable investment.
The diagnosis must come before the capital stack.
A practical division of labour
Philanthropic capital is best used where value is created but cannot easily be captured by one investor. It can fund research, project preparation, community engagement, training, early evidence and common infrastructure. It can also take a tightly defined first-loss position where that is necessary to test a new market. What it should not do is permanently compensate for a weak business model or guarantee the profits of a sponsor who could afford to take the risk.
Public capital should carry risks linked to public policy and market creation. Governments and public institutions can provide enabling infrastructure, regulatory certainty, targeted guarantees and long-term commitments where there is a legitimate development objective. Public money should be transparent, proportionate and tied to clear outcomes.
Development finance institutions sit between public purpose and commercial discipline. They can validate a market, structure longer-tenor or local-currency finance, provide political-risk cover, take mezzanine positions and establish environmental, social and governance standards. Their role is most useful when they use their balance sheets and credibility to make other investors comfortable enough to participate.
Commercial capital should take normal commercial risk once the exceptional barrier has been addressed. It should not receive public protection from every possible loss. Equity investors must still carry enterprise risk. Senior lenders must still underwrite repayment. Fund managers must still be accountable for judgement and performance.
The enterprise itself must also contribute. Founders and managers should bring commitment, transparent information, governance and an appropriate share of risk. Blended finance is not a substitute for operational discipline.

Twiga Foods (Nairobi, Kenya) scales informal supply chains using blended finance.
Source: IFC
An example of the stack working properly
Imagine a business that aggregates smallholder produce and processes it for local retailers. Demand exists, the unit economics are credible and the company has capable management. But small farmers lack quality systems, lenders do not understand the supply chain and the processing equipment requires a longer repayment period than local banks will offer.
A philanthropic partner could fund farmer training, traceability and independent evidence on crop quality. A development institution could provide a partial credit guarantee and support a local bank in extending the loan tenor. The local bank could provide senior finance in local currency. Commercial equity could fund the company’s growth and carry the ordinary upside and downside of execution.
Each layer addresses a different constraint. None should remain forever.
Once the quality data exist, the farmer network is established and lenders have seen repayment performance, future expansion should require less concessional support. That movement towards ordinary commercial finance is part of the impact.
Four tests for a credible structure
First, additionality: would the investment happen on reasonable terms without the concessional layer? If the answer is yes, the subsidy is probably unnecessary.
Second, minimum concessionality: is the public or philanthropic support limited to the smallest amount and shortest period required to unlock the investment? IFC’s blended-finance principles explicitly emphasise this discipline.
Third, alignment: does each investor earn a return that reflects the risk actually carried? A structure becomes unhealthy when one party receives private upside while another repeatedly absorbs avoidable losses.
Fourth, graduation: is there a path through which the project, enterprise or market becomes less dependent on concessional support? A good blended-finance transaction should build evidence, capability and confidence that reduce the need for blending over time.
Transparency connects all four tests. Investors and the public should be able to understand what support was provided, why it was necessary, who benefited and what would count as success.
Blending should make markets, not permanent subsidies
The OECD’s 2025 guidance frames blended finance around mobilising additional commercial capital for sustainable development, while also stressing local context, partnership and results. That is the correct ambition.
The best structure is not the one with the most participants. It is the one that solves a genuine constraint with the least distortion.
When blended finance works, public and philanthropic capital do not replace the market. They help create the conditions in which a responsible market can function.
That is the standard conscious capital should demand: not cheap money for good intentions, but the right risk in the right hands for long enough to build something that can endure.
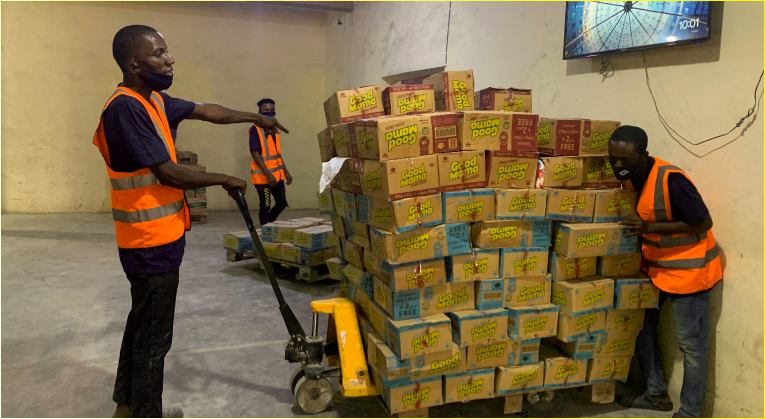
TradeDepot (Lagos, Nigeria) mobilises commercial capital to finance informal retailers responsibly.
(Source: IFC)