
conscious capital
The Exit Question: Can Impact Investors Leave Without Damaging What They Built?
Ajay Wasserman,
Founder, author, host of Conscious Capital
6 minutes
29 September 2026
Listen to the podcast here
Audio Title: The Exit Question: Can Impact Investors Leave Without Damaging What They Built?
Description:Discover why Africa's informal economy needs practical investment, not just formalisation. Explore how these sophisticated businesses employ millions.
Table of Contents
Introduction
Every private investment eventually faces an exit question.
A fund reaches the end of its life. A family office needs to recycle capital. A founder wants liquidity. A strategic buyer makes an attractive offer.
For a conventional investor, the central question is often price. For an impact investor, price cannot be the only question. We also need to ask what happens to the employees, customers, communities and purpose after ownership changes.
If the impact disappears as soon as the investor leaves, we may have financed a temporary programme rather than built a durable institution.
Exit begins at entry
Responsible exit planning should start before the investment is made.
At entry, investors should identify which parts of the impact thesis are vulnerable to a future owner. Is the company serving a low-income customer segment that a buyer might abandon? Are fair labour practices dependent on one founder? Does the environmental benefit rely on voluntary operating choices? Is impact data collected only because the current investor requires it?
These questions affect how the investment should be structured and how the company should be built.
The Operating Principles for Impact Management make impact at exit an explicit responsibility. The reason is straightforward: the life of the outcome may be much longer than the holding period of the capital.
An investor cannot control a company forever. But it can help create a business in which impact is sufficiently embedded to survive a change in ownership.
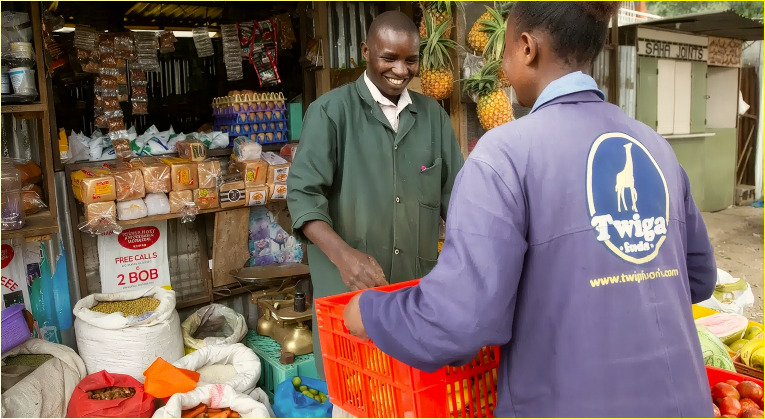
Twiga Foods delivery in Nairobi, Kenya, commercially embedding informal market vendors.
Source: Techpoint Africa
Build the mission into the economics
The strongest protection is a business model where impact and commercial success reinforce each other.
If serving an underserved customer is the source of growth, a buyer has less reason to abandon that customer. If energy efficiency reduces cost, environmental performance is not merely a voluntary promise. If retaining and developing employees improves productivity, fair treatment becomes part of the operating advantage.
Mission is most fragile when it exists only in the language of the investor presentation.
During the holding period, investors should help translate purpose into systems: board oversight, management incentives, product design, customer-protection rules, environmental standards, workforce practices and regular impact measurement. The company should understand its own impact thesis rather than simply report against a fund manager’s template.
Culture matters, but culture alone is not enough. People change. The discipline must also live in governance, processes and economics.
The buyer matters
Not every buyer is equally capable of carrying the mission forward.
A responsible investor should assess a potential purchaser’s strategy, reputation, time horizon, treatment of stakeholders and plans for the company. The highest offer may come from a buyer whose value-creation plan depends on cutting the very services, jobs or standards that created the impact.
That does not mean an impact investor must accept any price in the name of mission. Fiduciary duties and investor obligations are real. It means impact risk should be considered alongside financial and execution risk, not after the preferred bidder has already been chosen.
The Global Impact Investing Network has documented how investors such as Lok Capital screen buyers for mission alignment and strategic fit, including the potential effect on employees and the core business model. That is not sentimental investing. It is due diligence on whether the value built will endure.
The best future owner may also be the one able to scale the impact beyond what the current investor can achieve. A strategic buyer with distribution, technical capacity and long-term capital can be a responsible next steward. Exit can increase impact when the buyer is selected thoughtfully.
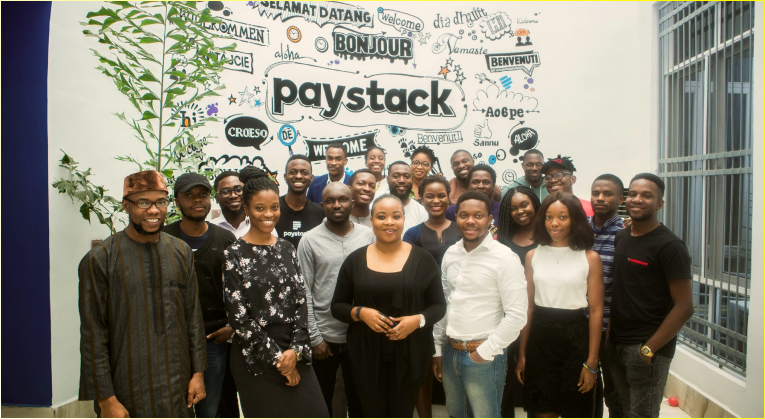
Paystack team in Lagos, Nigeria, acquired to scale merchant impact.
Source: African Business
Protect what is difficult to rebuild
Some outcomes need more than a good buyer.
Where mission risk is material, investors can use governance and contractual protections. These may include preserving specific customer commitments, environmental obligations, employee safeguards, reporting requirements or a board-level purpose mandate. In some structures, a foundation, trust, special shareholder or independent director may retain limited rights over defined mission matters.
These protections should be focused. If they are too broad, vague or impossible to enforce, they may discourage credible buyers without actually protecting impact. The aim is not to control the company from the grave. It is to protect the few commitments whose loss would fundamentally change what the enterprise exists to do.
Investors should also strengthen local leadership before exit. A mission that depends on the departing fund manager is not institutionalised. Management, employees, local partners and the board must be able to defend and develop it.
Protecting employment does not mean promising that no job can ever change. It means avoiding value-creation plans based on careless extraction, and ensuring that restructuring decisions recognise the human and community consequences attached to them.
Use the transaction structure
Exit does not have to happen in one step.
A phased sale can allow the new owner to demonstrate stewardship before taking full control. Earn-outs can link value to both financial and impact performance. A partial exit can give the company access to new capital while allowing the existing investor to support the transition. Management or employee ownership can preserve alignment where appropriate. Seller financing can create leverage to enforce important commitments, although it also retains risk.
The right structure depends on the company and the buyer. The principle is to use the mechanics of the transaction to support continuity rather than relying only on promises made during negotiations.
Impact considerations should be documented in the investment committee paper, buyer assessment and final transaction decision. If there is a trade-off, it should be acknowledged honestly.
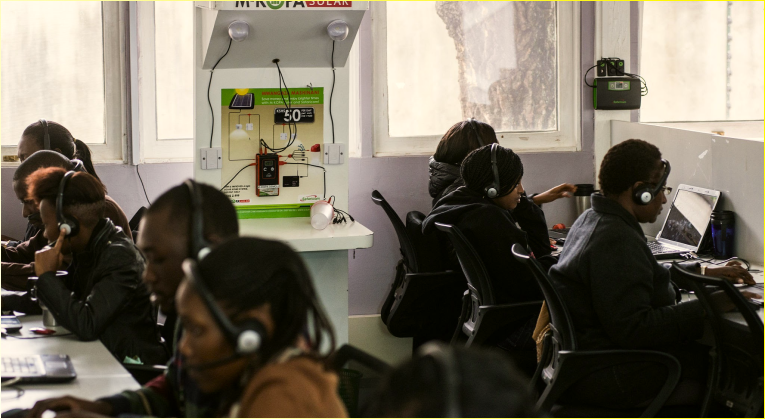
M-KOPA operations in Kenya, scaling informal energy access through structured partial investor exits.
Source: Acumen
Keep watching after the sale
Investors often measure impact until the day of exit and then stop.
That makes it difficult to know whether responsible-exit practices actually work. Where possible, the seller should agree on a limited period of post-exit reporting or maintain access to a small set of indicators. Even when formal rights are unavailable, investors can learn through management relationships, public information and stakeholder feedback.
The purpose is not endless surveillance. It is accountability and learning.
If a mission erodes after sale, future investment structures should improve. If a new owner scales the impact successfully, the market should understand what made that transition work.
A return should not require amnesia
Liquidity matters. Capital that never exits cannot easily be recycled into the next generation of enterprises.
But an exit is not only the moment an investor realises value. It is the moment the investor transfers stewardship.
The standard should therefore be higher than asking whether we built something valuable. We should ask whether we are leaving it in hands, systems and structures capable of carrying that value forward.
A good impact exit rewards the investor, strengthens the enterprise and gives the mission a life beyond the fund.
That is not a compromise between return and responsibility. It is the final test of whether the investment was truly conscious.